Morning Summary: It’s another day with a lot of numbers set for release with ag markets looking ahead to the weekly export sales and shipment data while financial markets have weekly initial and continuing jobless claims as well as June’s leading economic indicators on the docket. Overnight trade saw markets move down a familiar path with the U.S. dollar weaker, commodities in general higher, the euro back in the green, and U.S. stock indices riding high with Tesla. Though many markets seem to be reaching extremes (e.g. silver), something I’ll be talking about in my next Weekly Column, I don’t foresee a dramatic change in direction Thursday.
Soybeans: The soybean market was higher, again, overnight on moderate-to-light trade volume. The November issue registered only 13,700 contracts changing hands through early Thursday morning with deferred issues not even cracking the 2,000-contract level. As usual, this makes getting a read on spread activity difficult to start the day. On the other hand, national average basis is clear with the cmdty Natioal Soybean Basis Index (weighted national average) calculated at 39 cents under the lightly traded August contract Wednesday afternoon. This was 1/2 cent weaker than Tuesday’s calculation, what looks initially to be nothing more than a blip within a strong uptrend on the NSBI’s daily chart. U.S. soybeans are on a 7-day run of new export sales announcements, with continued strong commercial buying activity Wednesday hinting at this stretching to number 8 Thursday morning. However, weekly export shipments (for the week ending Thursday, July 16) are not expected to change the pace projection from coming in roughly 100 mb below USDA’s July estimate of 1.65 bb.
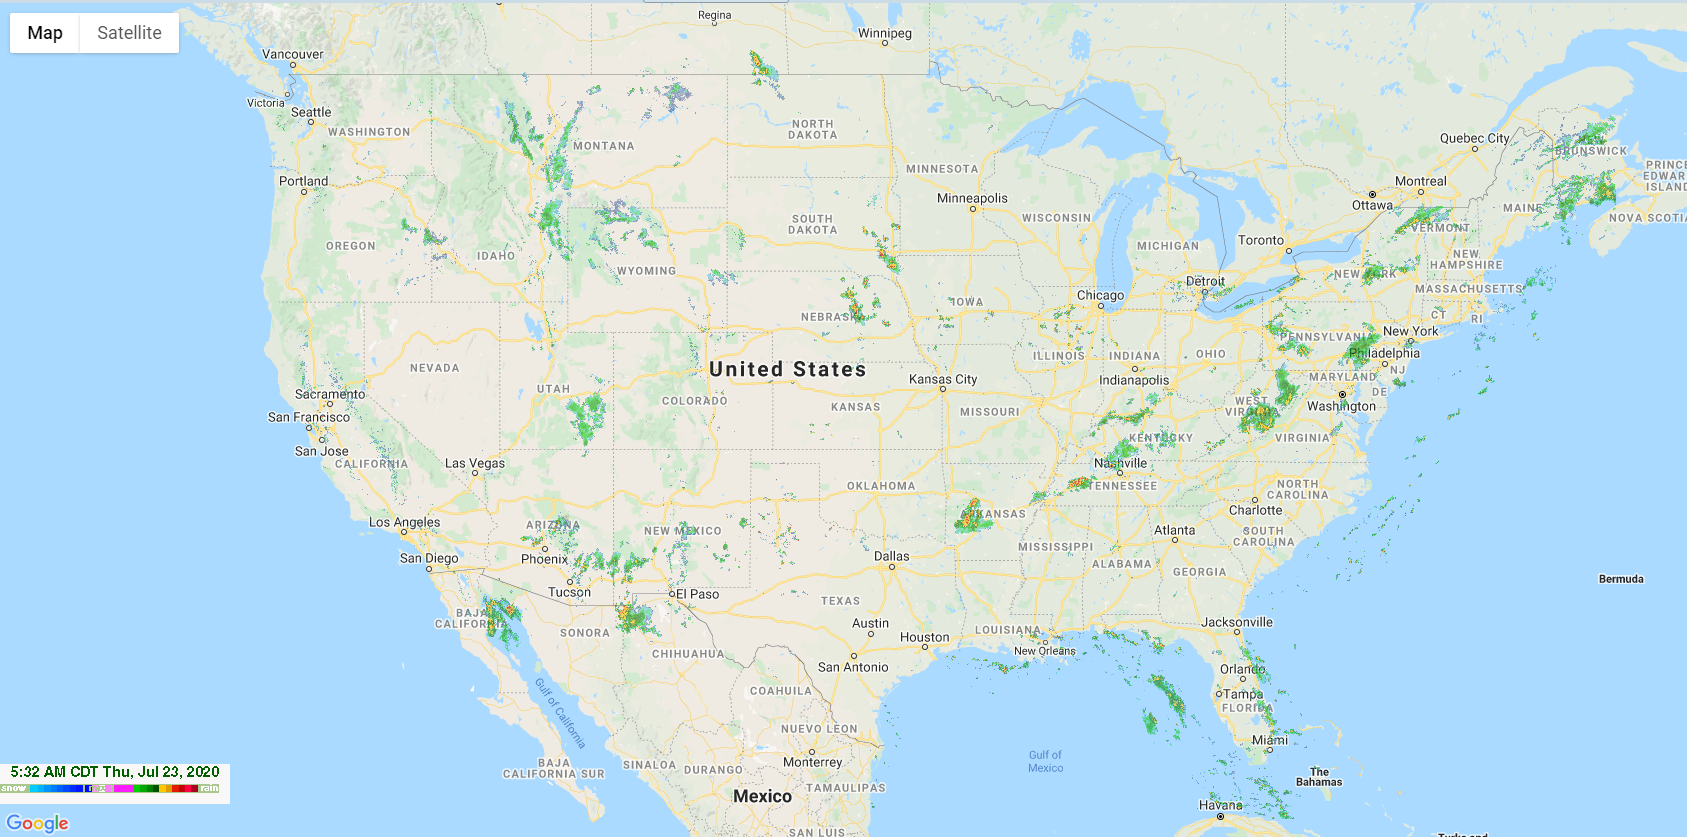
Corn: The corn market was quietly lower early Thursday morning with neither the September nor December issues cracking the 10,000-contract trade volume mark as of this writing. This isn’t overly surprising given corn’s tendency to stay quiet overnight as traders monitor weather. Speaking of which, a look at the map (see attached) to start the day shows mostly a blank slate with only popcorn showers scattered across the U.S Plains and Midwest. The last forecast I saw showed much of this same area could stay mostly dry through the weekend as temperatures ramp up once again. Wednesday saw national average basis weaken with the cmdty National Corn Basis Index calculated at 24 1/4 cents under September futures, down about 1/4 cent from Tuesday’s calculation. The NCBI remains in a consolidation pattern on its daily chart, still threatening a potential minor (short-term) bearish breakdown. This type of move should not be considered shocking, particularly if futures contracts follow-through on Wednesday’ bullish short-term technical signals (see Wednesday afternoon’s Chart of the Day).
Wheat: The wheat complex was under pressure to start the day on moderate-to-light trade volume. Most of the activity was seen in Chicago (SRW), with the September contract registering nearly 6,000 contracts changing hands. SRW wheat has seen strong commercial buying for much of this week, after Monday’s sharp sell-off, pushing both cash and futures higher. Still, the September contract looks to be in a minor (short-term) downtrend meaning we could see the Franklin Fish Similarity play out yet this week (for further discussion, see Thursday’s morning’s Chart of the Day to be posted during intermission). Kansas City (HRW) and Minneapolis (HRS) both moved lower on light trade volume, though spring wheat traders could get more active as the day goes along based on the latest weather forecasts.