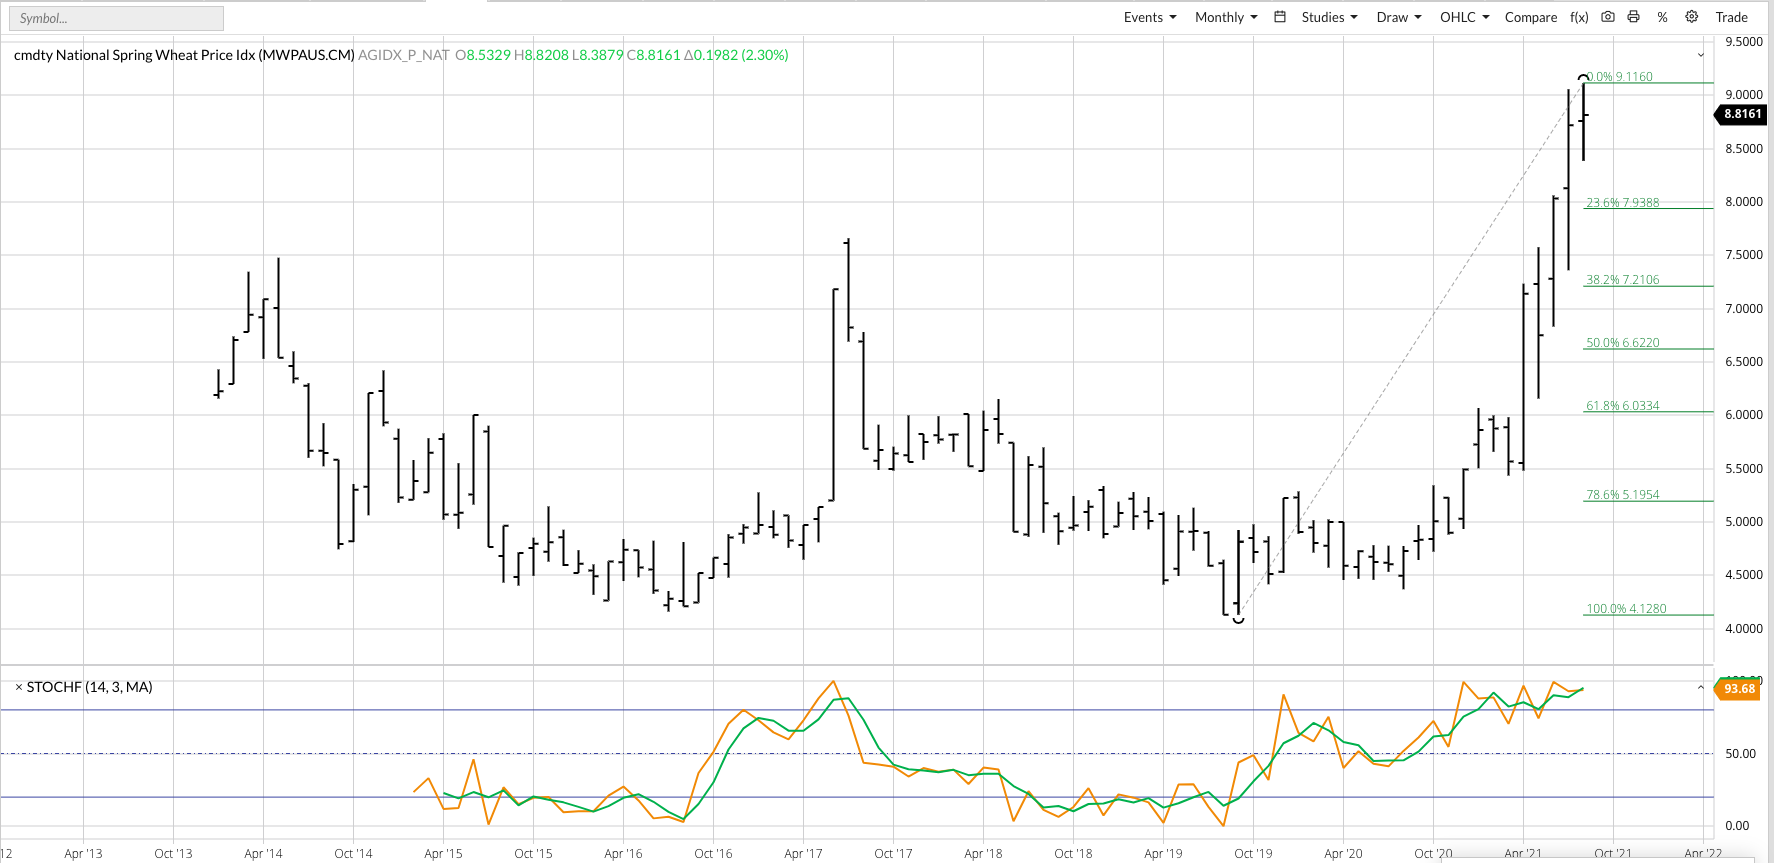
The cmdty National Hard Red Spring Wheat Price Index (HSPI, weighted national average cash price) extended its major (long-term) uptrend during August, hitting a high of $9.1160 before closing the month at $8.8161. From a structural point of view the HSPI is about as bullish as it comes, with the major uptrend supported by the futures market’s inverted forward curve from September 2021 through July 2022. Given this, it would not be surprising to see the HSPI continue to push higher during September despite what’s left of the 2021 harvest continuing to progress. However, there is one potential fly in the ointment. As August came to a close monthly stochastics established another bearish crossover above the overbought level of 80%, following up the previous bearish signal at the end of February. This means the market could see a bearish reversal over the coming months, though as of now there is nothing on emerging on the horizon.